Calculate Home Loan Interest: Rates and Repayment
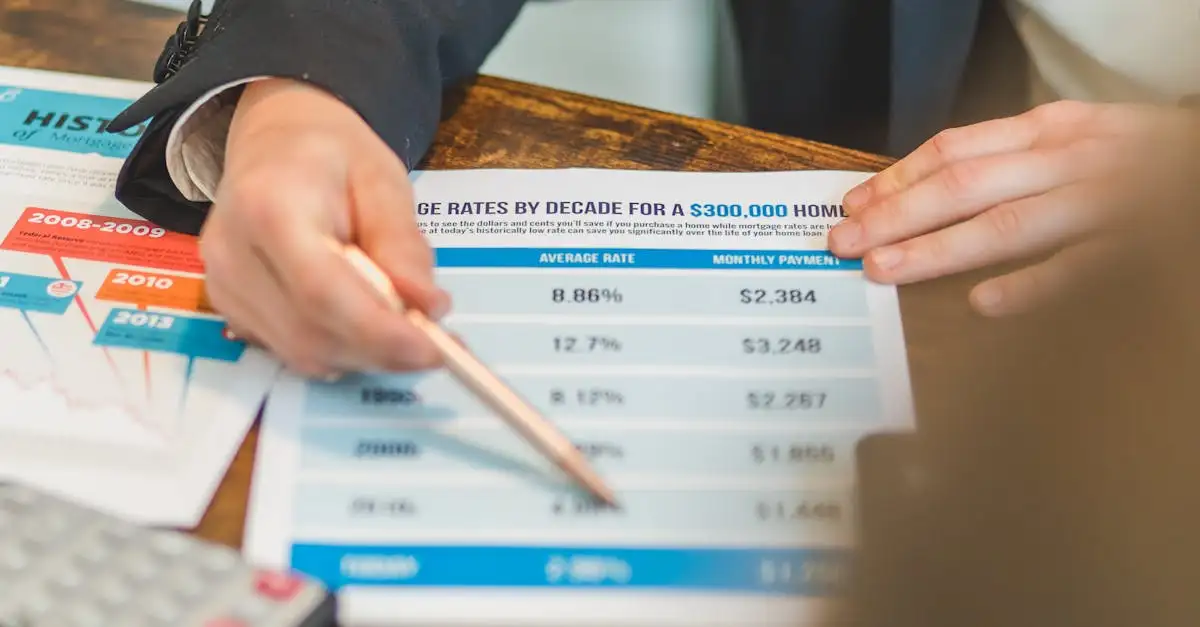
Thinking about buying a home is exciting. It represents a huge step forward. Suddenly, you face the practical side: the home loan. One of the biggest questions swirling in your mind centers on the cost. You wonder, "How much is interest on a home loan?" It feels like a big, complicated number, but understanding it puts you in control of your financial future. Let’s break down this essential part of homeownership together.
Understanding the True Cost of Borrowing
When you take out a mortgage, you are not just paying back the money you borrowed—the principal. You also pay a fee for the privilege of using that money over many years. This fee is the interest. It is the fundamental cost of financing your dream property. Think of it as the rent you pay for having immediate access to a large sum of money.
Your total home loan repayment involves both principal and interest. Over the life of a 30-year mortgage, the interest you pay often equals or even surpasses the original amount you borrowed. This fact highlights why understanding how that interest is calculated matters so much to your long-term budget.
 The Interest Rate: Your Starting Point
The actual amount of interest you pay directly depends on your interest rate. Lenders offer different rates based on various factors about you and the current economic climate. This rate is usually expressed as a percentage.
What influences your specific interest rate for a home loan? Several key things shape this figure:
- Your Credit Score: A strong credit history shows lenders you manage debt responsibly. Lenders reward lower risk with lower interest rates.
- The Loan Term: Shorter terms (like 15 years) usually have lower interest rates than longer terms (like 30 years).
- Down Payment Amount: A larger down payment reduces the lender's risk, often leading to a better interest rate.
- Market Conditions: Broader economic factors, set by central banks, affect what lenders charge everyone.
Fixed vs. Adjustable: Which Rate Structure Fits You?
When you explore options for calculating home loan interest payments, you encounter two main types of interest rates. Choosing between them impacts your financial predictability for years to come.
VIDEO: How Do Interest Rates Affect Your Mortgage and Monthly Payment? Interest Rates Explained
The Security of a Fixed Rate Mortgage
A fixed-rate mortgage means your interest rate stays exactly the same for the entire life of the loan. If you secure a 4% rate today, you pay 4% interest in year one, year fifteen, and year thirty. This offers immense peace of mind. You always know precisely what your principal and interest payment will be.
For many homebuyers seeking budget stability, the fixed rate is the preferred route. You eliminate the uncertainty of future economic shifts affecting your monthly housing expense. You lock in your rate today. Before committing to a fixed rate, it's essential to ensure you first learn how to lower your home loan interest rate.
The Fluctuations of an Adjustable Rate Mortgage (ARM)
An adjustable-rate mortgage, or ARM, starts with a fixed rate for an initial period—perhaps three, five, or seven years. After this introductory period ends, the interest rate adjusts periodically based on a specified market index.
ARMs often start with lower initial interest rates than fixed loans. This can mean lower payments early on, which attracts some buyers. However, you must prepare for the possibility that the rate—and thus your payment—rises significantly later. When you consider an ARM, thoroughly investigate the loan's adjustment caps to understand your maximum potential payment.
How Interest Gets Paid: Amortization Explained
The most confusing part of understanding how much interest you pay on a mortgage involves amortization. This is the schedule that dictates how your monthly payment is divided between principal and interest over time.
In the early years of your home loan, the vast majority of your monthly payment goes toward covering the interest owed. Because the interest is calculated on the large outstanding loan balance, that interest portion is substantial.
As you continue making payments, your principal balance slowly decreases. Since interest is calculated on the remaining balance, the amount of interest in your monthly payment shrinks over time. Conversely, the portion of your payment going toward the principal increases. This shift is the essence of amortization.
Imagine a 30-year loan:
- Year 1: 80% of your payment might be interest; 20% is principal.
- Year 15: This balance shifts, perhaps becoming 50% interest and 50% principal.
- Year 28: Most of your payment now chips away at the principal balance.
This structure means that if you plan to sell your home relatively soon, you pay significantly more interest overall than someone who stays put for the full term.
Helpful references
Broaden your understanding of Calculate Home Loan Interest: Rates and Repayment with these carefully selected reads.
Strategies to Reduce Your Total Interest Paid
You have some power over the final interest figure on your loan. Making strategic choices can substantially lower the total interest expense over your homeownership journey. These tactics focus on either lowering the rate or paying down the principal faster.
Consider these methods for minimizing your interest burden:
- Make Extra Principal Payments: Any extra money you send in beyond the required payment goes straight to the principal balance. This immediately lowers the base upon which future interest calculates. Even small, consistent extra payments make a big difference over thirty years.
- Shorten the Loan Term: Opting for a 15-year mortgage instead of a 30-year mortgage drastically reduces the total interest paid, even if the monthly payment is higher. You pay interest for half the time.
- Refinance When Rates Drop: If market rates fall significantly below your current rate, refinancing your home loan interest calculation can secure you a lower ongoing percentage. This effectively reduces the cost of borrowing the remaining balance.
Comparing Loan Offers: How to See the Real Cost
When lenders present you with loan estimates, never focus only on the initial monthly payment. That number can be misleading, especially if one offer has a very low introductory rate that spikes later. You need transparency regarding the total cost.
Always ask for the "Total Interest Percentage" or the "Total Cost of Credit" over the full term of the loan. This figure cuts through the noise and shows you the true price tag associated with borrowing that specific amount of money from that specific lender.
Pay attention to the Annual Percentage Rate (APR). The APR includes the interest rate plus certain other charges and fees rolled into the cost of borrowing. It provides a more accurate, standardized comparison point between different lenders offering various loan products. A lower interest rate doesn't always mean a lower overall cost if the upfront fees are very high.
Frequently Asked Questions About Home Loan Interest
How often is home loan interest calculated?
Typically, interest on a home loan is calculated daily but is charged to you monthly as part of your required installment payment.
Does paying more than the minimum payment reduce the interest paid?
Yes, absolutely. Any extra money you apply directly to the principal balance reduces the amount on which future interest charges are calculated, saving you money over time.
What happens to the interest rate if I pay off my loan early?
If you pay off your loan early, you stop accruing interest immediately on the remaining balance. You pay less total interest than originally scheduled, even if the initial rate was high. Understanding the amortization schedule is key to figuring out exactly how much interest you save, which is different from how you might calculate interest-only loan payments.


