Understanding Mortgage Points: Lowering Loan Interest Rates
Navigating the world of loans often feels like stepping into a dense forest. There are many terms to learn, and sometimes even simple words take on surprising meanings. You are probably looking to secure financing, perhaps for a new home or a significant purchase. When you look at the loan documents, you invariably see the term "point." What exactly is a loan point? Understanding this concept is crucial because it directly affects the total cost of borrowing money.
Demystifying the Loan Point: More Than Just a Dot
A loan point, sometimes called an origination point, is essentially a fee. Think of it as prepaid interest that you pay upfront when you finalize your mortgage or another type of secured loan. Lenders charge these points to cover the costs associated with creating the loan. It also acts as an additional way for them to make a profit on the transaction.
When someone talks about a point, they usually mean one percent of the total loan amount. If your loan is for $200,000, one point equals $2,000. This might seem like a small piece of the whole, but these fees can add up quickly, especially on larger borrowings.
 What Do Loan Points Actually Pay For?
You might wonder why you pay this fee right at closing instead of it being spread out over the life of the loan. Lenders use points for several key functions. Recognizing what these functions are helps you decide if paying points makes sense for your financial situation. You are essentially paying for services rendered and for adjusting your interest rate.
- Processing the loan application and underwriting the risk.
- Covering administrative costs tied to setting up the financing.
- Buying down, or lowering, your actual interest rate over time.
Discount Points Versus Origination Points
The term "point" can sometimes feel ambiguous because lenders use it in a few different contexts. Generally, when discussing loan costs, you encounter two main types: discount points and origination points. Recognizing the difference between these two options informs your negotiation strategy significantly.
Discount Points: Trading Cash Now for Lower Payments Later
Discount points are entirely optional. You choose to pay these points to "buy down" your interest rate. If you plan to stay in your home for many years, paying discount points often saves you a substantial amount of money over the loan's lifetime, even after accounting for the upfront cost. This is a classic trade-off: more cash today for lower monthly payments tomorrow.
Consider this scenario. Paying two discount points on your mortgage might lower your interest rate by a quarter of a percent. You need to calculate your "break-even point." This is the exact time—measured in months—when the savings from the lower payment match the initial cost of buying those points. If you plan to move before you reach that break-even point, paying discount points is likely not the best financial move for you.
Origination Points: Fees You Cannot Avoid
Origination points, on the other hand, are not optional rate adjustments. These are the lender’s fees for setting up the loan. They cover the work involved in evaluating your creditworthiness and preparing the loan documents. Often, lenders structure their fees so that one point covers their base administrative costs. You might see these listed under different names on your closing disclosure, but they function as a standard charge for initiating the lending process.
It is important for you to look closely at your Loan Estimate form. Lenders must clearly state all these charges. If a lender offers you a loan with zero points, they are either absorbing the cost into a higher interest rate or they are charging you entirely through other closing costs.
How Points Affect Your Overall Borrowing Cost
When you evaluate loan offers, you must look beyond just the interest rate. The inclusion of points significantly changes your effective borrowing cost. A loan that seems to have a fantastic interest rate might hide substantial upfront fees if it requires you to pay two or three points. Even when considering points, there are still ways to find strategies to lower your home loan interest rate.
You should always calculate your Annual Percentage Rate, or APR. The APR takes into account the interest rate *plus* most of the upfront charges, like points, spread out over the term of the loan. This gives you a more accurate, standardized measure for comparing different loan offers. When comparing lenders, a lower APR usually signals a better overall deal, assuming all other factors remain equal.
Negotiating Loan Points
Are loan points negotiable? Absolutely, especially discount points. Lenders set the initial offer, but you possess the power to negotiate. If you are a strong borrower with excellent credit, you might be able to convince the lender to reduce or even waive origination points.
Regarding discount points, you can negotiate the number you wish to purchase. Perhaps the lender offers three options: pay zero points at a high rate, pay one point at a medium rate, or pay two points at a lower rate. You decide how much you want to pay upfront based on your personal timeline for keeping the loan.
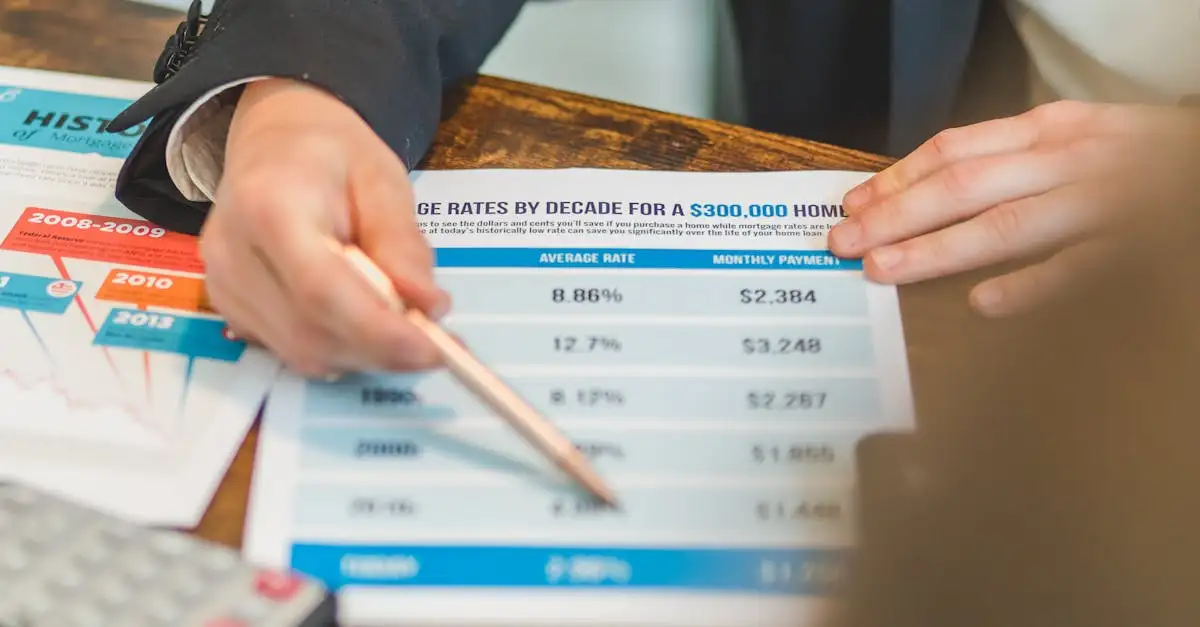
Remember this crucial detail: when interest rates are very high, paying discount points becomes much more attractive because you immediately secure a lower long-term rate. Conversely, when interest rates are historically low, paying points might not offer significant enough savings to justify the large cash outlay at closing.
Zero-Point Loans and Their Hidden Details
Sometimes, you see loan options advertised as having "zero points." This sounds wonderful—no upfront fees! However, you need to investigate the fine print. A zero-point loan almost always means the lender charges you a higher interest rate than they would if you paid discount points.
The lender needs to recover their costs and make their intended profit somehow. With a zero-point loan, they shift that recovery to the ongoing monthly payments. For someone needing to minimize cash needed at closing, a zero-point option works perfectly. For someone planning to keep the financing for decades, paying points might save thousands. Understanding how lenders determine these low home loan interest rates can help borrowers make an informed decision about points.
You must assess your budget and your long-term plans when deciding how many loan points are right for your specific financing needs.
*Frequently Asked Questions About Loan Points
What is a standard amount for loan points?
Typically, one point equals one percent of the total loan amount. Lenders often quote fees ranging from zero to three points initially.
Do I have to pay points on a loan?
Origination points are lender fees and usually required, though they are often negotiable. Discount points are entirely optional; you choose whether or not to pay them to lower your interest rate.
Are points tax-deductible?
In many cases, points paid to secure a mortgage on your primary residence are deductible as prepaid interest in the year you paid them. You should always check with a tax professional for guidance specific to your situation.


