Home Loan Refinance Costs: What You Need to Know
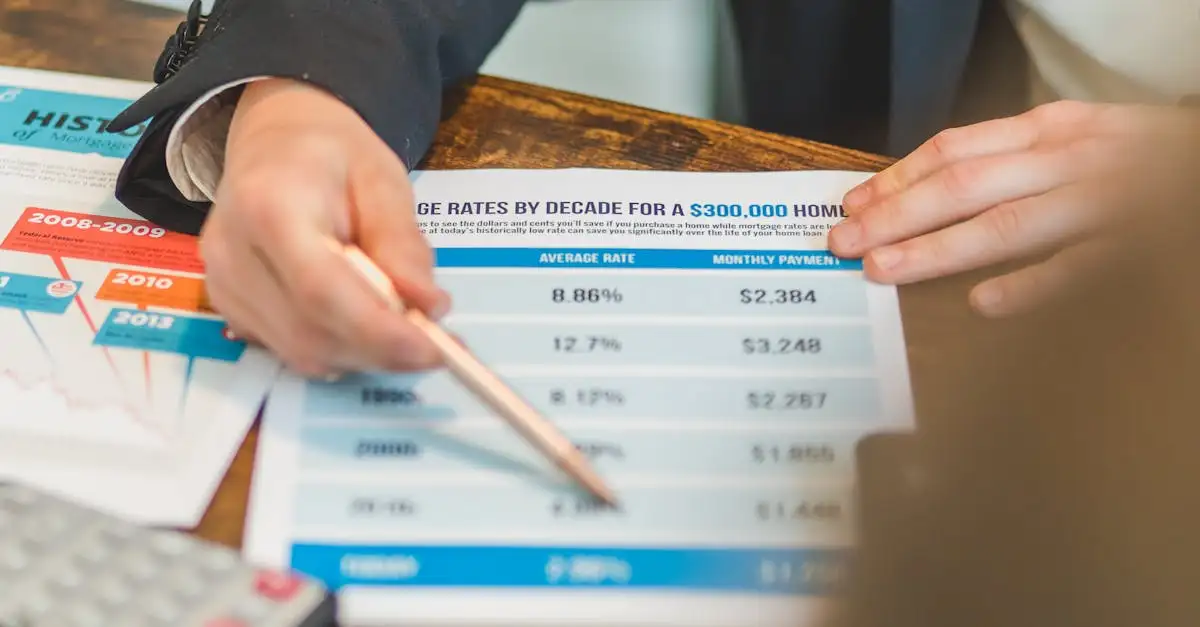
Thinking about refinancing your home loan feels like a big step. It often means you want a better financial situation for your future. Perhaps you seek a lower monthly payment, or maybe you plan to tap into your home's equity. Understanding the true cost of refinancing your home loan removes the mystery. It helps you make a smart, informed decision about your housing finances.
The Price Tag of a Home Loan Refinance: What You Really Pay
When you refinance, you replace your existing mortgage with a new one. This new loan comes with its own set of fees. These costs are often what people mean when they ask, "What does it cost to refinance a home loan?" It’s not just about the new interest rate you secure; there are upfront expenses you need to budget for. Ignoring these costs is a common mistake that can erase the benefits of a lower rate.
These closing costs generally range from 2% to 5% of your total loan amount. For example, if you are refinancing a $200,000 mortgage, you might expect to pay between $4,000 and $10,000 in total fees. You need to know where this money goes so you feel completely prepared.
Application and Processing Fees
Lenders charge fees just to start the paperwork. Think of this as the administrative cost of getting your new loan application reviewed. These fees cover the time your loan officer and processing team spend working on your file. Sometimes lenders bundle these under a general "processing fee." Always ask for a breakdown of these initial charges.
VIDEO: Refinance 101 - Mortgage Refinance Explained
 Appraisal Fees: Knowing Your Home’s Worth
Lenders always require a professional appraisal before approving a refinance. They need to confirm that your home is still worth what you claim it is. This protects their investment. You pay the appraiser directly for this service. Appraisal fees typically fall between $300 and $600, depending on where you live and the size of your home. This cost is necessary for securing the best interest rates.
Title Search and Insurance Costs
When you took out your first mortgage, a title search confirmed you legally owned the property without major liens against it. The refinance process requires another title search. Lenders want assurance that the title remains clear. You also pay for title insurance. This protects both you and the new lender against future claims on the property's ownership. These title-related expenses make up a significant portion of the total closing costs for refinancing a mortgage. If you are refinancing a VA loan, understanding VA loan closing costs and who pays how much can help you prepare financially.
Lender Fees: Origination and Underwriting
This is often the biggest chunk of the refinance cost. The lender charges an origination fee. This covers the cost of creating the new loan agreement. Underwriting fees cover the process of the lender verifying all your financial documents—your income, debts, and credit history. These fees are sometimes quoted as a percentage of the loan, often around 1% of the loan amount.
You might see an option to pay "points" to lower your interest rate. A point is an upfront fee equal to 1% of the loan amount. Paying points effectively buys down your interest rate for the life of the loan. You must calculate if the monthly savings outweigh this initial cost over time.
Can You Avoid Paying These Refinance Costs?
The idea of paying thousands upfront often makes people hesitate. You often hear about "no-closing-cost refinancing." This sounds ideal, doesn't it? However, there is no truly free lunch in finance. When a lender offers no closing costs, they are not absorbing the expenses. Instead, they roll those costs into your new loan amount or charge you a slightly higher interest rate.
Deep-dive links
Enrich your knowledge about Home Loan Refinance Costs: What You Need to Know with these essential readings.
The Trade-Off: Higher Rate vs. Upfront Cash
If you choose a no-closing-cost option, you essentially finance your closing fees. This means you pay interest on those fees every month for the next 15 or 30 years. If you have a small budget right now and cannot afford the upfront fees, this option makes sense. However, if you plan to stay in the home for a long time, paying those fees directly usually saves you more money overall.
Use a refinance calculator to compare the total cost over five years for both scenarios: paying closing costs now versus paying a higher rate later. Seeing the hard numbers helps you decide which approach to refinancing your home loan best suits your financial timeline.
Escrow and Prepaids: Temporary Holding Costs
Not every charge you pay at closing is a permanent fee. Some money goes into an escrow account. This is money the lender holds to pay your future property taxes and homeowner's insurance premiums. They ask you to prepay several months' worth of these items at closing to set up the escrow account correctly. While this adds to your cash needed at closing, it is not a fee paid to the lender; it is money held on your behalf for future bills.
Tips for Lowering Your Refinance Expenses
You have some control over the total expense associated with securing a new mortgage rate. Being proactive helps reduce the overall cost to refinance your home loan. One effective strategy for lowering these costs involves understanding who pays the fees and negotiating them with your lender.
- Shop Around Aggressively: Get rate quotes from at least three different lenders. Their fees and interest rates vary widely. A small difference in origination fees between lenders adds up fast.
- Improve Your Credit Score: A higher credit score qualifies you for better rates and fewer lender fees. Pay down small debts before applying.
- Negotiate Fees: Some lender fees, like processing fees, are negotiable. Ask if they can reduce or waive certain charges, especially if you have a strong financial profile.
- Accept a Slightly Higher Rate: If you are set on avoiding upfront costs, select a loan where the interest rate is only slightly higher than the lowest available option. This keeps your closing costs low while managing the long-term rate increase.
- Waive the Appraisal (Sometimes): In some cases, if you have significant equity or meet certain low-risk criteria, your lender might offer an appraisal waiver. This saves you the appraisal fee immediately.
When you receive your Loan Estimate form—a required disclosure document—study every line item. This document clearly shows you exactly what costs you assume when refinancing your mortgage. Transparency is your best friend in this process.
Frequently Asked Questions About Refinancing Costs
How long does it take to pay back the closing costs?
This is called the "break-even point." You find this by dividing the total closing costs by the amount you save monthly on your new payment. If costs are $5,000 and you save $250 a month, your break-even point is 20 months.
Do I pay an appraisal fee if my refinance is denied?
Yes, you usually pay the appraisal fee upfront. This fee pays the third-party appraiser for their time and report, regardless of the lender's final decision on your loan application.
Are property taxes included in refinance closing costs?
Portions of property taxes are included as prepaid items in your closing costs, as lenders collect money upfront to fund your escrow account.


